Steps in lease accounting
Details for lease accounting
Let us assume the following details for lease accounting as per Ind AS 116
Lease start date: 1-Apr-2019
Lease end date: 31-Mar-2024
Lease payments: Rs. 2,75,000
Payment frequency: Annual – payable at the end
Incremental borrowing rate: 9%
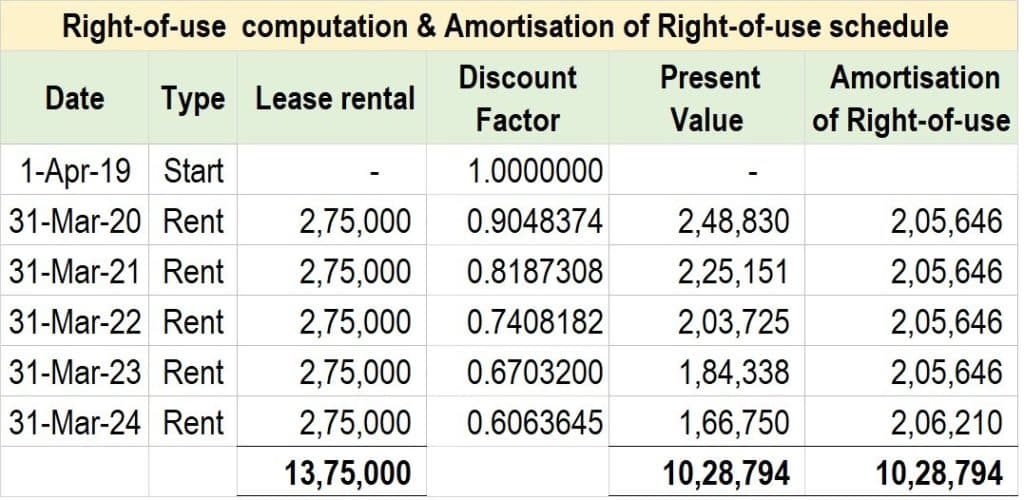
Step 1: Calculate the right-of-use
The right-of-use is first calculated as follows:
Step 2: Prepare amortisation schedule
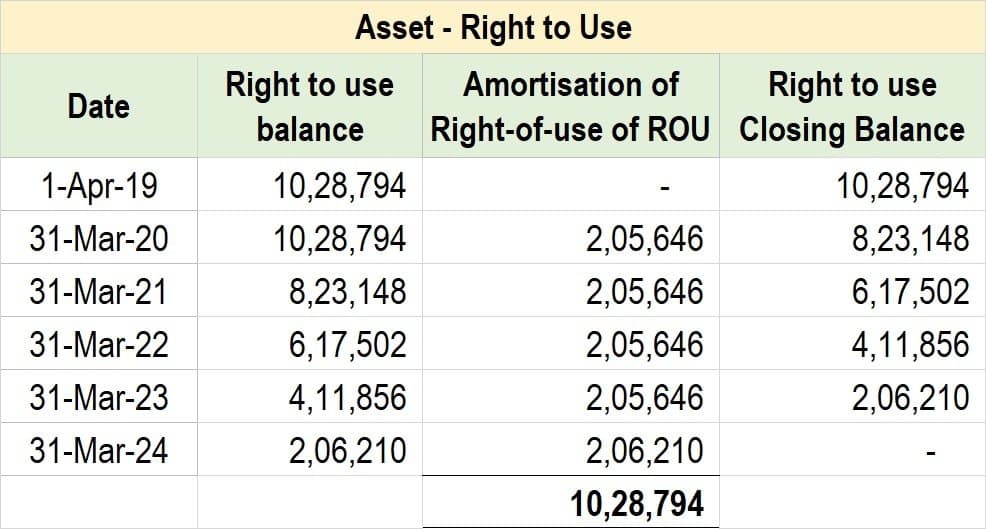
The amortisation schedule based on straight line method is calculated as follows:
Step 3: Calculate Lease Liability
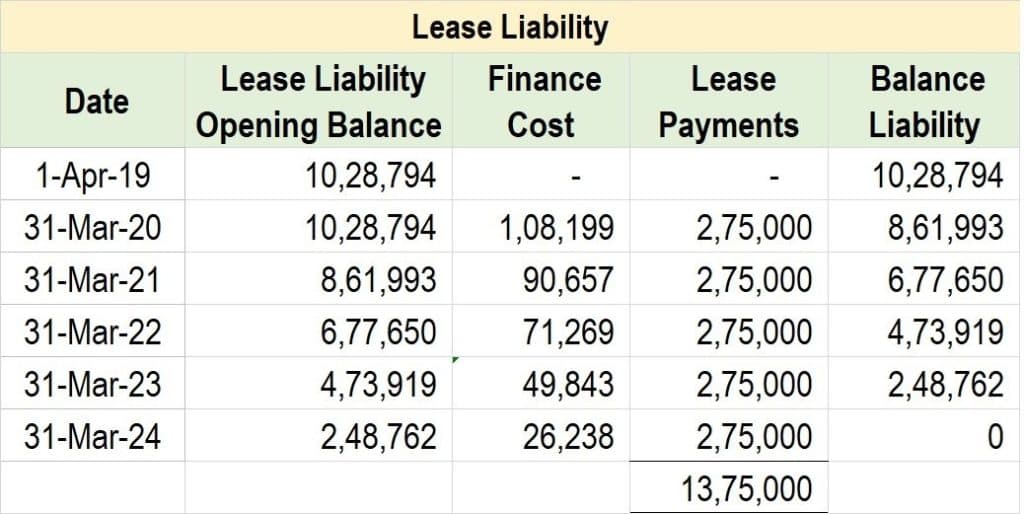
The lease liability is computed as follows:
Step 4: Calculate the finance charges
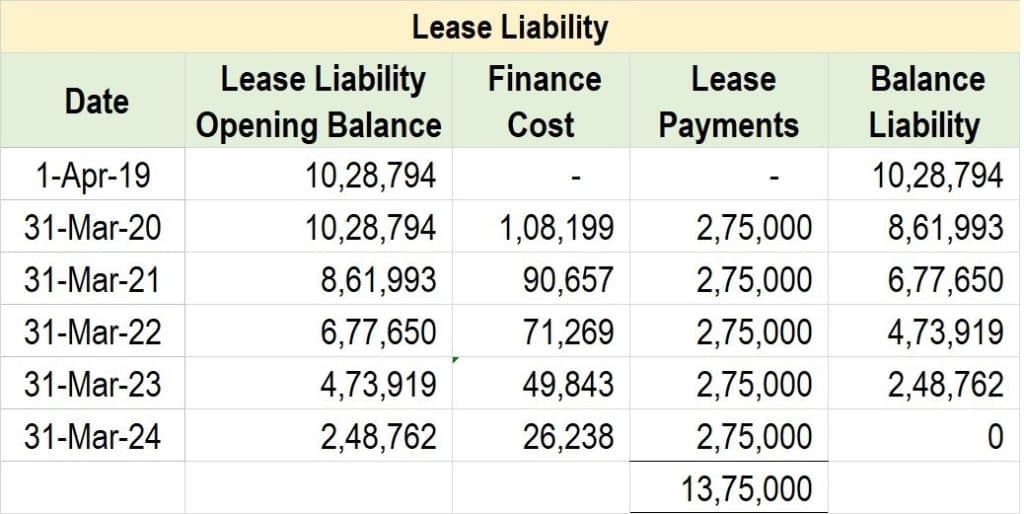
The finance charges for the lease liability is calculated as follows:
Lease Accounting Software Pricing
No post found!
What is the difference between operating lease and finance lease?
Lease accounting, lease period extended after year 1 – Journal entries
Lease accounting, interest-free deposit lease period extended after year 1
Lease accounting Journal Entries for Modification
Lease accounting with an interest-free deposit
Journal entries for lease accounting
Operating lease vs financing lease
Lease Accounting as per IFRS 16 vs. AS 19
How to compute right-to-use asset
How to determine the lease term as per the standard
How to separate the components of a lease contract
How to identify a lease contract as per the lease accounting standard
Lease Accounting as per Ind AS 116
Presentation & Disclosure – lease accounting standard
What is the new lease accounting standard
Lease Accounting as per IFRS 16
Extracts from Annual reports – Lease Accounting
Exemptions that can be availed in lease accounting