Mutual Agreement Procedure
- Mutual Agreement Procedure (‘MAP’) is a procedure set out in most treaties which permit designated Government representatives to work together to resolve international tax disputes including issues involving double taxation, questions regarding residential status, tax recovery etc.
- MAP is used to eliminate double taxation that can arise from transfer pricing adjustments.
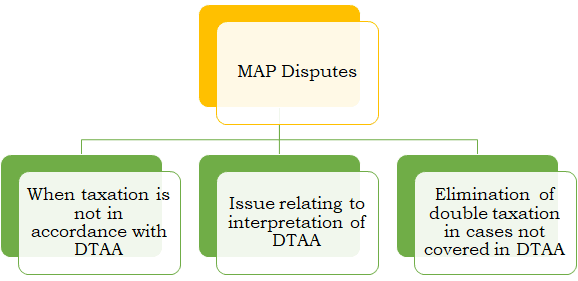
Eligibility for MAP
- MAP application can be filed by a person when he considers that he has not been taxed in accordance with the Treaty.
- Even if such person has other remedies such as appeal process under the domestic laws, MAP can be initiated. MAP can be applied in the country in which he is a resident or a national.
- This can be presented within three years from the date of receipt of notice of the action which gives rise to taxation not in accordance with convention.
Steps in MAP application
- Background: Brief facts and background of the case.
- Summary: Summary of Revenue contentions; net tax and interest impact arising out of the TP adjustment, if any.
- Documents: All supporting documentation in the nature of return of income, orders etc.
- Precedents: Relevant judicial precedents and their applicability in the taxpayer case.
MAP process in India
- Overseas taxpayer: Overseas taxpayer can invoke MAP if there exists double taxation or taxation not in accordance with the DTAA.
- Overseas Competent Authority: Application will be forwarded by overseas CA to Indian CA if it considers that application is appropriate.
- Indian CA: Indian CA can consider the application for discussion.
- Additional Information: Both the Indian and Overseas CA can seek information.
- Indian Tax administration: In case the case is resolved by the CA and accepted by the taxpayer, then Indian tax administration will communicate this to the tax officer. MAP solution should be given effect within 90 days.
Drawbacks of MAP
- It is a time consuming process, often taking 2–3 years for conclusion.
- Participation of taxpayer is often very limited since it is between CAs of different countries.
- There may not be suspension of collection of taxes till the resolution of MAP and interest will also be ticking.
Income from transaction with Non-Residents – Transfer Pricing
Transfer pricing adjustment and consequence
Dispute Mitigation strategies in transfer pricing
Advance Pricing Agreements (APA)
Fundamentals of Base Erosion and Profit Shifting – Transfer Pricing
Anti-Avoidance measures in certain jurisdictions – Transfer pricing
Returns, Audit and other miscellaneous provisions – Transfer pricing
Determination of ALP – Transfer Pricing
Arm’s Length Principle – Transfer Pricing
Specified Domestic Transactions – Transfer Pricing
Secondary Adjustment – transfer pricing
International Transaction – Transfer Pricing
Additional reporting by Multinational companies – Transfer pricing
Economic analysis – Transfer Pricing
Limitation of interest deductions – transfer pricing
Penalties for non-compliance – Transfer Pricing