Fundamentals of Base Erosion and Profit Shifting – Transfer Pricing
Introduction
- In the past few decades, the world has seen large movement of capital and investment from developed and developing countries.
- This has resulted in huge economic development, boosted trade and increases foreign direct investment in various countries.
- Many developing countries (low – cost locations) saw boon in their manufacturing activity and become operation hub for many MNEs.
- This also accelerated growth, innovation and created jobs.
- Taxes are the main revenues for the economy. Once cross border activities increased, there were many instances of double-taxation and need to eliminate the same was noticed.
- Progressively, Governments entered bilateral tax agreements often called as Double Taxation Avoidance Agreements (‘DTAA”) with other countries for elimination of double taxation and resolution of disputes.
- The global MNEs started adopting sophistication in tax planning thereby reducing the overall tax burden of the MNE.
- Sometimes these tax planning methods were very aggressive, touching the boundaries of exploiting legal arbitrage which often leads to Base Erosion and profit shifting (‘BEPS’).
Adverse effect of BEPS
- BEPS refers to tax planning that exploit gaps in the domestic laws and mismatches in tax rules to make profit disappear for tax purposes or to shift profits to locations where there is little or no economic activity but the taxes are low. This has adverse effect on the economy for many reasons including:
- In developing countries, tax revenue is used for funding public investments and welfare measures. By depriving the tax revenues, these countries are underfunded and deprived of economic growth.
- When the business reduce their tax burden by shifting profit to low tax jurisdiction, other taxpayers, particularly individuals, suffer since they have to shoulder the increased share of tax burden, which is unfair.
- This also results in a situation that the place where economic activity is carried out receives less or no tax while profits reside in a jurisdiction which has low or zero tax.
- Also, the enterprises which operate only in domestic market or family owned business who do not have the ability to shift the profit abroad suffer.
- Fair competition is harmed.
Why there is disparity?
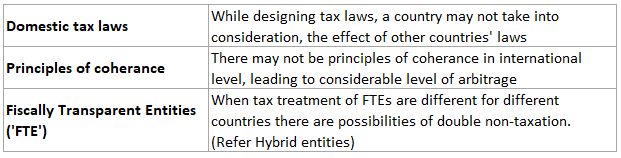
- Taxation is the core of a country’s sovereignty. These domestic tax laws of each country lead to gaps and mismatches which are broadly discussed below:
BEPS action plan
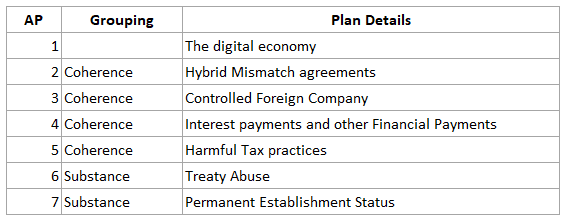
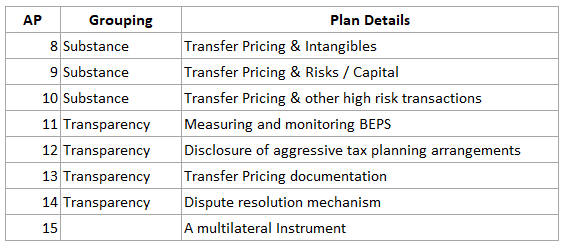
- The OECD published a report addressing the BEPS issues by publishing draft Action Plans (‘AP) in July 2013 which came to finality in October 2015.
- It has 15 APs to address BEPS in a comprehensive manner and set a deadline for implementation.
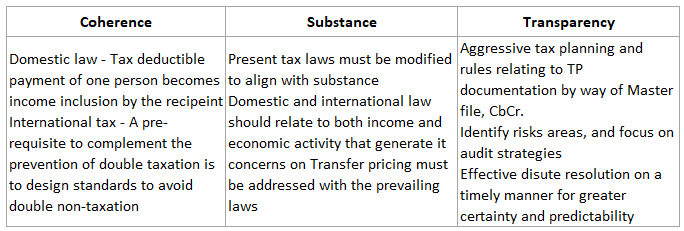
- The action plans are based on three main principles:
BEPS overview of Action Plan
Question
Why there is often tax arbitrage between countries?
- Domestic laws may not take in to account the effect of its laws on other countries and lack of coherence and differential tax treatment may cause tax arbitrage
- Tax arbitrage happens when MNEs try to evade taxes
- Tax arbitrage happens because countries want to preserve its tax sovereignty
Answer a.
Question
In the context of BEPS, what is meant by coherence?
- Domestic and international law should relate to both income and economic activity that generate it
- Identifying risks areas, and focus on audit strategies between taxing countries
- Tax deductible payment of one person becomes income inclusion by the recipient and thereby preventing double non-deduction
Answer c.
Coherence means tax deductible payment of one person becomes income inclusion by the recipient which is taken care in domestic law and may be difficult to practice in international law thereby paving way for double non-deduction.
Income from transaction with Non-Residents – Transfer Pricing
Transfer pricing adjustment and consequence
Dispute Mitigation strategies in transfer pricing
Advance Pricing Agreements (APA)
Anti-Avoidance measures in certain jurisdictions – Transfer pricing
Returns, Audit and other miscellaneous provisions – Transfer pricing
Determination of ALP – Transfer Pricing
Arm’s Length Principle – Transfer Pricing
Specified Domestic Transactions – Transfer Pricing
Secondary Adjustment – transfer pricing
International Transaction – Transfer Pricing
Additional reporting by Multinational companies – Transfer pricing
Economic analysis – Transfer Pricing
Limitation of interest deductions – transfer pricing
Penalties for non-compliance – Transfer Pricing